A savings account shows the same balance month after month. Nothing seems to change. Yet, at the supermarket, the same amount of money buys a little less. A property owner notices higher maintenance costs, while an investor watches stock prices react to another central bank announcement.
This is the quiet side of economic instability. Capital can lose purchasing power without disappearing from an account.
Inflation, interest rates and currency movements create different challenges for wealth preservation. The question is not simply where money can earn the highest return, but which assets can retain their value when economic conditions change.
Consider how four common investment options compare:
| Asset | Main advantage | Main limitation |
|---|---|---|
| Bank deposits | Liquidity and predictable interest | Inflation can exceed returns |
| Stocks | Long-term growth potential | Market volatility |
| Real estate | Tangible ownership and rental income | High costs and limited liquidity |
| Physical gold | International recognition and diversification | No interest income; price fluctuations |
There is no universal winner. Each asset responds differently to economic pressure, which explains why investors increasingly look beyond traditional savings products.
Why Investing in Precious Metals Is Back in Focus
The renewed interest in investing in precious metals reflects a shift in how people perceive financial security. Gold, in particular, has regained attention as investors look for assets that are not directly dependent on the performance of banks, corporations or individual currencies.
The figures are telling. According to the World Gold Council’s Gold Demand Trends: Full Year 2025, global gold demand reached approximately 5,002 tonnes in 2025. Investment demand increased by 84% year-on-year to 2,175 tonnes, while central banks added another 863 tonnes to their reserves. Bar and coin demand also reached a 12-year high.
These figures suggest that interest in gold extends beyond private investors. Financial institutions and central banks are also using it as part of their reserve diversification strategies.
Why does gold attract attention during uncertain periods?
First, its supply cannot be expanded at the same pace as fiat currency. Mining requires investment, time and access to increasingly challenging deposits. Second, gold has an established international market, making it recognisable across borders. Third, physical ownership offers a different relationship with wealth compared with holding shares or financial products.
Still, gold is not a magic shield against economic problems. Its price can fall, sometimes sharply. The stronger argument for holding it is diversification rather than an expectation of permanent price increases.
Inflation, Interest Rates and Currency Pressure
Inflation gradually changes the mathematics of saving. An account paying 2% interest may appear attractive until inflation reaches 3%. The nominal balance increases, but its purchasing power declines.
Interest rates influence this equation. When central banks raise rates, deposits and government bonds may become more appealing. At the same time, borrowing becomes more expensive, which can put pressure on property markets and corporate valuations.
Currency risk adds another layer. A Swiss investor holding assets denominated in US dollars may experience a different return once those assets are converted back into francs. Even a profitable investment can deliver a weaker result because of exchange-rate movements.
This is why looking at returns in isolation can be misleading. Investors need to consider inflation, taxes, fees and currency exposure together.
Four Assets, Four Different Roles
Bank Deposits
Deposits are useful for emergency savings and short-term financial commitments. Their main strength is accessibility.
However, they are rarely designed to generate substantial long-term growth. When interest rates remain below inflation, cash gradually loses purchasing power.
Stocks
Shares provide exposure to business growth. Companies with strong brands, pricing power and healthy balance sheets may adapt to inflation better than weaker competitors.
But stock markets can be unpredictable. A sudden change in interest-rate expectations or geopolitical tensions can trigger widespread selling.
For long-term investors, diversification across sectors and geographical markets can help reduce concentration risk.
Real Estate
Property offers something financial securities cannot: physical utility. People need homes, businesses need premises, and rental properties can generate regular income.
Yet real estate comes with significant responsibilities. Maintenance, taxes, insurance, financing costs and vacancies all affect the final return.
Property is also difficult to liquidate quickly. Selling an apartment is not quite like selling a listed share.
Physical Gold
Gold has a different investment profile. It does not produce cash flow, but it can provide diversification and exposure to an internationally traded tangible asset.
Its price is influenced by interest rates, currency movements, central bank activity and investor sentiment.
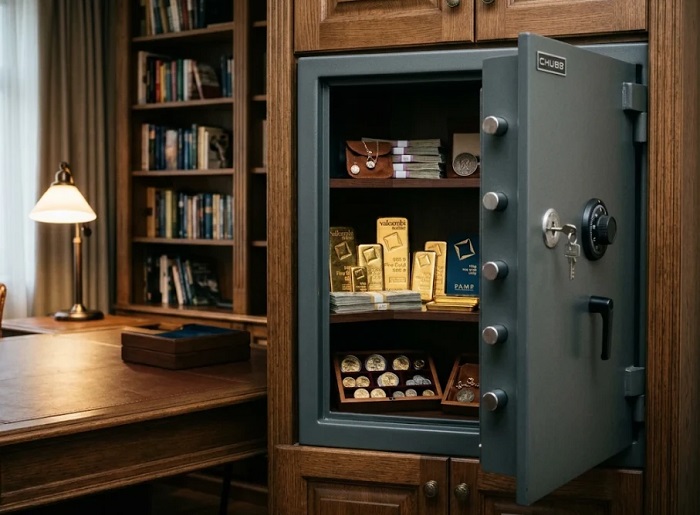
Physical bullion also requires secure storage and careful attention to authenticity, purity and resale conditions.
A Practical Approach to Wealth Preservation
One common mistake is trying to predict the next economic crisis and repositioning an entire portfolio around that prediction.
A more balanced approach focuses on resilience, with diversification helping investors manage exposure to different economic risks, as explained in the IMF’s research on financial stability
Think of a portfolio as a building. Deposits provide accessible reserves, stocks contribute growth potential, property adds tangible value, and gold introduces another source of diversification. The structure works best when no single component carries the entire burden.
A few practical principles can help:
- Keep liquidity available. Short-term expenses should not depend on selling long-term investments.
- Avoid excessive concentration. Depending on one currency, company or asset class increases exposure to specific risks.
- Consider real returns. Always compare investment performance with inflation.
- Understand ownership costs. Fees, taxes, storage and transaction spreads can reduce returns.
- Review periodically. Changes in personal circumstances and economic conditions may require adjustments.
There is also a useful distinction between buying an asset because its price is rising and buying it because it serves a defined purpose. The second approach usually leads to more disciplined decisions.
Wealth Preservation Checklist
Before making any long-term investment decision, consider the following:
- Investment horizon – Is the money intended for short-term needs or long-term preservation?
- Inflation exposure – Could rising prices erode the expected return?
- Currency diversification – Are all assets dependent on one currency?
- Liquidity – Can the investment be converted into cash when necessary?
- Risk tolerance – Are temporary price declines financially manageable?
- Ownership costs – Have taxes, fees, insurance and storage been considered?
- Diversification – Does the investment complement existing assets?
A checklist will not eliminate uncertainty, but it can prevent decisions driven purely by market excitement or fear.
Security Through Diversification
Economic instability changes the way people think about money. Inflation challenges the traditional idea of cash as a reliable store of value, interest-rate movements influence investment returns, and currency fluctuations introduce risks that are easy to overlook.
Deposits remain useful for liquidity, stocks offer growth opportunities, and real estate provides tangible ownership.
Physical gold brings a different set of characteristics, particularly its international recognition, limited supply and potential diversification benefits.
The renewed demand for real assets reflects a search for balance rather than a rejection of traditional investments. Gold, for example, cannot replace every other asset or guarantee protection from losses. Its role is more specific: to provide an additional store of value within a broader financial strategy.
Ultimately, preserving capital is not about finding an investment that never falls. It is about building a structure that can withstand changing economic conditions without depending entirely on one outcome.